Stocks rose for the week on relief that a soft jobs report could keep an October Fed rate hike off the table, while strong AI capex, and optimism for the upcoming Q3 earnings season added a bullish bias. Strong earnings beats and upward guidance should help markets look past broader macro headwinds and could support a rally into year-end.
Key Highlights:
- The services industry slowed in September. The ISM Services Index slipped to 54.9 from 55.4 in August. Numbers above 50 indicate expansion while those below signal contraction. Although new orders and business activity/production remained strong, stretched supply chains and prices paid by businesses reaching their highest level in more than four years weighed on the overall index.
- The U.S. trade deficit widened to $105.6 billion in August from $92.8 billion in July amid an AI-fueled surge in capital goods imports. Despite the robust demand for AI, imports as a rule generally subtract from GDP calculations and will mathematically result in a net drag on Q3 GDP growth. Still, the Atlanta Fed’s GDPNow tracker estimates GDP will increase a healthy 3.60% in the third quarter.
Stocks Advance Despite Macro Headwinds
In a clean sweep for the Street, all three major indices finished higher for the week as investors remained optimistic a soft jobs report would keep an October Fed rate hike off the table and as the calendar turns to the Q3 earnings season next week. AI stocks led the way, fueled by strong capital expenditure on goods and services supporting the massive AI buildout. The week’s gains came despite surging yields, energy prices, and persistent inflationary pressures. Treasuries continued to hit multi-decade highs with the 10-year Treasury yield briefly hitting 5.37% while the 30-year touched 5.73%. Despite investors’ relief the soft jobs data will halt an October Fed rate hike, Fed speakers continued to reiterate inflation remains too high and more rate hikes will be needed to tame prices. Meanwhile, oil prices turned sharply higher with WTI crude swinging from a low of $86+ a barrel on Tuesday to $92+ a barrel on Friday as tensions remained high in the Middle East and as Hurricane Isaias churned in the Gulf. As of Thursday, oil companies have shut in about 1.3 million barrels per day, or around 63% of total U.S. production in the Gulf. Depending on Isaias’ path, an estimated 2% of the country’s refining capacity could be impacted at a time when fuel markets are already tight. That could potentially send prices higher for consumers as domestic demand for goods and services remains high.
A weekly gain for equities looked unlikely, given the turmoil afflicting the bond and oil markets for much of the week. However, traders were willing to dismiss the inflationary readings in the ISM and the potential oil and refinery supply disruptions from the storm in the Gulf, instead choosing to look forward to the start of the Q3 earnings season next week. Analysts expect it to be a good one with EPS growth forecasted to rise 30.60% year-over-year. The energy sector is expected to do the heavy lifting with the sector’s earnings projected to increase 123% due to the ongoing Middle East tensions. The AI trade is also expected to put up big numbers with the tech and communication services sectors estimated to post earnings growth of 66.50% and 47.8%, respectively. A combination of EPS beats and positive guidance should help investors move past macro headwinds, keeping stocks in rally mode into year-end.
The Week Ahead
The Q3 earnings season kicks off with big banks set to report. In economic news, CPI, PPI, and existing home sales are the highlights of the week.
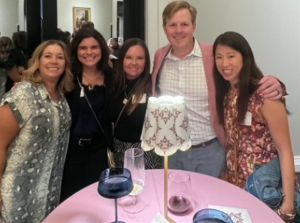
Celebrating Art, Conversation, and Connection with a Night at the Museum
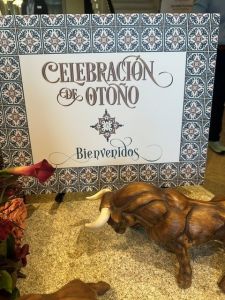
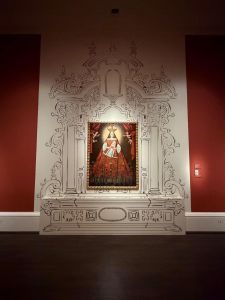
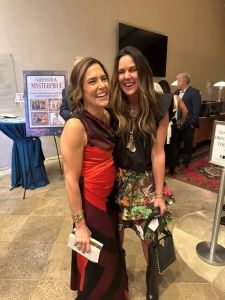
The warm weather gave way to a welcome respite just in time for our Celebración de Otoño at The Meadows Museum on October 7th. The break in the heat made for a lovely evening to gather, celebrate, and welcome the fall season.
We are immensely grateful to all of our clients and friends who attended and filled the evening with connection and conversation. We hope all of our guests enjoyed the Spain-inspired evening, including a menu of paella served in mini cast iron skillets with a selection of savory bites. Two signature sangria cocktails were aptly named El Matador and La Reina. The sweet treat at the end of the night was the freshly fried churros dusted with cinnamon sugar and served with dulce de leche, chocolate sauce, and vanilla whipped cream. Additionally, at the end of the evening, guests took home almendrados—Spanish almond cookies.
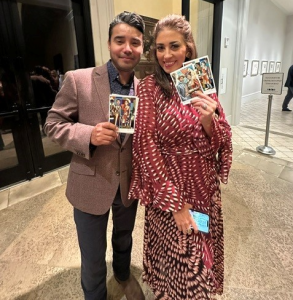
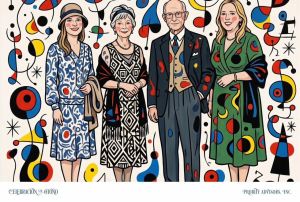
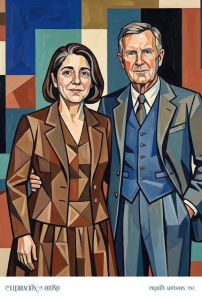
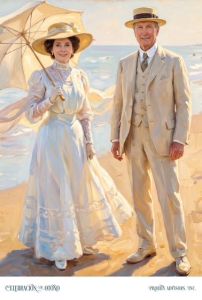
One of the evening’s highlights was the AI-powered photo booth where guests could “step into a masterpiece.” Inspired by the famous artists featured in the museum, photo-booth pictures were transformed into one-of-a-kind keepsakes based on various styles of Spanish art—a memorable reminder of the evening.
To everyone who joined us: a huge gracias! Thank you for showing up and for bringing your energy, your stories, and your conversation and connection. The night served as a reminder of what makes our work—and the people we share it with—so special. We couldn’t have asked for a better evening or better company.
Adios until next time!
Probity Advisors, Inc.